
Indiana is a hyperscale state with a thin retail market. AWS’s Project Rainier campus in New Carlisle (2,200 MW at full build) and Google’s Fort Wayne campus (1,200 MW) dominate the operating base.
The next largest operating sites are a fraction of their size: Digital Crossroad Hammond (20 MW), DataBank IND2 in Indianapolis (10 MW), and Lifeline Data Centers’ Eastgate campus, which publishes no capacity figure.
Tax policy is the draw. Indiana waives its 7% sales tax on data center equipment and electricity for up to 50 years, yet business power costs 13.93¢/kWh, slightly above the U.S. average, and local opposition has killed or stalled four major projects since 2025.
Hyperscalers and AI tenants buying power at scale get one of the best deals in the country. Enterprises shopping for cheap power or a deep retail colocation market will find more next door in Chicago.
Indiana Data Center Tracker
125data center listings
Indianapolis 48South Bend 28La Porte 18Fort Wayne 159 others 16
Indianapolis holds 48 of Indiana’s 125 listings, while the largest campuses rise in New Carlisle, Fort Wayne, Hobart and Lebanon.
Market Snapshot
Largest Operating Data Centers In Indiana
These are the five largest operating sites by published capacity. AWS New Carlisle and Google Fort Wayne dwarf the rest, and every other listing appears on the map, with operating sites in green and planned ones in coral.
- AWS New Carlisle Campus (Project Rainier)New Carlisle, full build2,200 MWOperational
1,200-acre campus that will ultimately draw 2.2 GW
- Location:
- New Carlisle, St. Joseph County
- Operator:
- Amazon Web Services
- Online since:
- October 2025
- Workload:
- Project Rainier AI cluster for Anthropic
- Google Fort Wayne CampusFort Wayne, full campus1,200 MWOperational
12-building campus on more than 700 acres, with the first phase running since December 2025
- Location:
- Fort Wayne, Allen County
- Operator:
- Investment:
- $2 billion
- Workloads:
- Google Maps, Gemini and Google Cloud
- Digital Crossroad HammondHammond, facility max20 MWOperational
105,000 sq ft facility supporting up to 20 MW, per Digital Crossroad
- Location:
- Hammond, Lake County
- Operator:
- Digital Crossroad
- Tenant:
- CoreWeave, per city records
- DataBank IND2Indianapolis, facility power10 MWOperational
Purpose-built 40,000 sq ft data center with liquid cooling
- Address:
- 650 W Henry St, Indianapolis
- Operator:
- DataBank
- History:
- Formerly Lightbound, acquired in 2018
- Lifeline Data Centers EastgateIndianapolisNot publishedOperational
80,000 sq ft building with 2N power and cooling on a 41-acre campus
- Address:
- 401 N Shadeland Ave, Indianapolis
- Operator:
- Lifeline Data Centers
- Hardening:
- F5 tornado resistant, per Lifeline
Also operating, shown on the map as green circles: , .
Largest Planned Data Centers In Indiana
Amazon’s Hobart campus and Meta’s Lebanon campus account for 3,400 MW of the 3,775 MW shown here.
- AWS Hobart CampusHobart, full build2,400 MWPlanned
2.4 GW campus within a $15 billion Northern Indiana investment
- Location:
- Hobart, Lake County
- Developer:
- Amazon Web Services
- Meta Lebanon CampusLebanon, gigawatt-scale1,000+ MWIn development
Gigawatt-scale campus in the LEAP district
- Location:
- Lebanon, Boone County
- Developer:
- Meta
- Buildings:
- 12 listed
- Logix I CampusFrankfort, full campus300+ MWPlanned
13-building campus development
- Location:
- Center Township, Clinton County
- Developer:
- Logistix Property Group
- Metrobloks Indianapolis IND A1Indianapolis, full build75 MWUnder construction
$500 million AI-ready facility, with first capacity targeted for Q1 2027
- Address:
- 2505 N Sherman Dr, Indianapolis
- Developer:
- Metrobloks
- Microsoft La Porte CampusLa PorteNot publishedUnder construction
Campus that broke ground in June 2026
- Location:
- La Porte, LaPorte County
- Developer:
- Microsoft
- Tax breaks:
- Microsoft dropped its local property tax abatement request in March 2026
- Google Morgan County CampusMorgan CountyNot publishedUnder construction
390-acre campus in Monroe Township, with construction under way in 2026
- Location:
- Monroe Township, Morgan County
- Developer:
- Vantage Pittsboro CampusPittsboroNot publishedPlanned
Three data center buildings on 285 of 618 rezoned acres
- Location:
- Pittsboro, Hendricks County
- Developer:
- Vantage Data Centers
Also planned, shown on the map as coral circles: , , , , , , , , , , , , , , , .
Largest Colocation Facilities In Indiana
Retail colocation centers on the Henry Street telecom cluster in downtown Indianapolis, with smaller sites in South Bend and Fort Wayne.
- Lifeline Data Centers Fort WayneFort Wayne84,000 sq ftColocation
Colocation and private cloud space
- Address:
- 7601 S Anthony Blvd, Fort Wayne
- Operator:
- Lifeline Data Centers
- Lumen Indianapolis 1Indianapolis20,000 sq ftColocation
AC and DC power with generator and battery backup
- Address:
- 1902 S East St, Indianapolis
- Operator:
- Lumen
- US Signal Indianapolis IN02Indianapolis19,017 sq ftColocation
North-side facility about 10 miles from downtown
- Address:
- 6325 Morenci Trail, Indianapolis
- Operator:
- US Signal
- Raeden IndianapolisIndianapolis10,000 sq ftColocation
Carrier-agnostic site with 330 kW of N+1 power
- Address:
- 800 Oliver Ave, Indianapolis
- Operator:
- Raeden
- Cogent Data Center IndianapolisIndianapolis4,400 sq ftColocation
42U cabinets with UPS and generator backup
- Address:
- 13 S Davidson St, Indianapolis
- Operator:
- Cogent Communications
- Lumen South Bend 1South Bend4,067 sq ftColocation
DC power with diverse fiber connectivity
- Address:
- 1140 Franklin St, South Bend
- Operator:
- Lumen
- Netrality Indy Telcom CenterIndianapolisNot publishedColocation
Downtown telecom campus with 14 carriers and the Midwest Internet Exchange
- Address:
- 701 to 733 W Henry St, Indianapolis
- Operator:
- Netrality
- GAP Union StationSouth BendNot publishedColocation
One of Indiana’s two carrier hotels, per Global Access Point
- Address:
- 506 W South St, South Bend
- Operator:
- Global Access Point
More operating colocation, shown on the map as green squares: , , , , , , , , , , , , , , , , , .
Choose a category to switch the list and highlight its sites on the map. Click any site card to find it on the map, or click a marker to jump to its card. Pins are approximate, and each MW figure carries the basis shown beside it.
Data sourced from Data Center Map, EIA, NOAA, PJM, DCD and the Indiana Capital Chronicle, checked October 10, 2026. Listings count individual buildings, and the lists show the largest sites in each category.
Why Colocate In Indiana?
Indiana wins on tax treatment, land, climate, and proximity to Chicago. It loses on power price, grid mix, retail supply, and local approvals.
The six factors below weigh each side.
1. Market Access And Latency
Indiana sits at the center of the Midwest. Indianapolis connects to Chicago, Columbus, Cincinnati, Louisville, and St. Louis along the I-65, I-69, I-70, and I-74 corridors, and long-haul fiber follows those same routes.
Northwest Indiana works as an extension of the Chicago market. Digital Crossroad’s Hammond site sits on the Illinois border, so tenants get Chicago-area reach with Indiana land costs and tax treatment.
The rest of the large-campus map serves a different buyer. New Carlisle, Fort Wayne, Hobart, and Lebanon are hyperscale campuses built around power and land, and they offer enterprise buyers no retail access.
2. Network Connectivity And Peering
Indianapolis holds the state’s interconnection, centered on the Henry Street telecom cluster downtown. Netrality’s Indy Telcom Center at 701 to 733 W Henry St hosts 14 carriers and the Midwest Internet Exchange, and DataBank IND2 sits a block away at 650 W Henry St.
South Bend is the second hub. Global Access Point’s Union Station building at 506 W South St is one of Indiana’s two carrier hotels, which gives northern Indiana a local interconnection point.
The depth stops there. Chicago’s carrier hotels hold far more networks and cloud on-ramps, so Indiana buyers that need dense peering run transport to Chicago and treat Indianapolis as an edge or backup site.
3. Power, Cost, And Sustainability
Indiana offers no power price advantage. The business rate averaged 13.93¢/kWh over the 12 months to July 2026, slightly above the 13.85¢/kWh U.S. average.
For buyers comparing colocation pricing across the Midwest, that rate is roughly neutral. Any savings in Indiana come from tax, and the power line on the invoice will look about the same as elsewhere.
The grid runs mostly on fossil fuel. Coal supplied 45% of generation in 2025 and natural gas 36%, a combined 81%, with wind at 9% and solar at 6%. Buyers with carbon targets will struggle to claim clean power from the local grid.
Demand is surging faster than supply. Indiana Michigan Power expects its Indiana peak load to jump from 2,800 MW to more than 7,000 MW by 2030, driven by new large loads.
Regulators have tightened the terms in response. Under I&M’s large-load tariff, approved in February 2025, customers above 70 MW at one site or 150 MW in aggregate sign contracts of at least 12 years, pay exit fees to leave early, and need state approval to cut contracted capacity by more than 20%.
The grid splits between two markets. I&M’s territory, home to the AWS and Google campuses, sits in PJM, while NIPSCO and most other utilities run in MISO, so power terms and capacity costs vary by county.
4. Tax Policy And Incentives
Tax policy is Indiana’s strongest card. Since 2019, qualified data centers have been exempt from the state’s 7% sales tax on equipment and electricity, with terms up to 50 years for investments above $750 million.
The math is large. Every $100 million of exempt servers, networking, and cooling gear saves $7 million, and the electricity exemption takes 7% off every power bill for the life of the certificate.
For a hyperscale campus refreshing hardware every few years, that exemption is worth more than any electricity discount the state could offer. It explains why AWS, Google, Meta, and Microsoft chose Indiana despite average power prices.
Lawmakers kept the exemption intact in 2026. A proposal to eliminate it was stripped from legislation, and the final law, House Bill 1210, adds only a small local payment: data centers certified after June 30, 2026 pay no more than 1% of their exempt state sales tax on electricity to the local government. Certificates already issued are excluded.
The industry points to the payoff. A study commissioned by the Data Center Coalition credits data centers with more than $327 million in state and local tax revenue in 2023. The state has never published its own estimate of what the exemption costs.
5. Workforce And Ecosystem
Indiana’s labor market is tight. Unemployment was 3.3% in July 2026, well below the 4.1% national rate, and labor force participation of 63.1% runs above the 61.4% national figure.
That helps the state’s economy and hurts hiring. Electricians, controls technicians, and facility staff are hard to find when six hyperscale campuses compete for the same crews.
Indiana’s manufacturing base supplies industrial electrical and mechanical skills, and Purdue, Indiana University, and Notre Dame feed engineering talent into the state.
Retail colocation buyers in Indianapolis feel the labor squeeze least, since long-running downtown operators run staffed sites with remote hands.
6. Risk And Resiliency
Indiana’s natural hazard profile is moderate. Tornadoes and severe storms are the main threats: in 2024, a 75 mph derecho and an EF2 tornado hit near Indianapolis.
Facilities need wind-rated roofs, protected rooftop equipment, and generator plans for multi-day outages.
The climate helps. Indianapolis averages 53.8°F over the year and stays under 65°F in 8 of 12 months, which gives operators long free-cooling seasons and lower cooling costs than Sun Belt markets.
The biggest risk is political. Google withdrew its 468-acre Project Flo rezoning in Franklin Township in September 2025 ahead of a likely council denial, QTS abandoned an 800-acre Porter County campus after protests, Surge Development pulled a 775-acre Hancock County plan, and American Tower withdrew a Pike Township project in February 2026.
Approval risk is the largest unpriced cost of building in Indiana. Buyers backing new campuses need a realistic plan for a rezoning fight, and buyers who need certainty get it in buildings that already exist.
Key Cities Or Submarkets In Indiana
Indiana’s data center map splits into three groups: a retail and interconnection core in Indianapolis, hyperscale campuses across the north, and a ring of land-stage projects around the capital.
The five submarkets below run from the deepest retail supply to the most speculative pipeline.
1. Indianapolis
Indianapolis is Indiana’s only real retail colocation market, with 48 of the state’s 125 listings. The Henry Street telecom cluster downtown holds the interconnection core, anchored by Netrality’s Indy Telcom Center and DataBank IND2, both profiled below.
Retail options beyond Henry Street are small. Raeden offers 10,000 sq ft and 330 kW of N+1 power at 800 Oliver Ave, Cogent runs 4,400 sq ft at 13 S Davidson St, and Lumen, US Signal, and Lifeline round out the market.
The largest new project is Metrobloks IND A1 at 2505 N Sherman Dr, a $500 million, 75 MW facility targeting first capacity in Q1 2027. Neighbors in Martindale-Brightwood have opposed it.
Marion County is hostile ground for large new campuses. Both recent large-campus proposals, in Franklin and Pike townships, were withdrawn under neighborhood pressure.
The Indianapolis colocation market suits enterprises, managed service providers, and healthcare and government buyers that need anything from a few cabinets to a small suite with downtown carrier access.
2. New Carlisle And South Bend
St. Joseph County holds Indiana’s largest operating campus. AWS’s Project Rainier site in New Carlisle, profiled below, is an AI training campus built for Anthropic, and it sits in I&M territory on the PJM side of the grid.
South Bend has 28 listings, the second-highest count in the state. Global Access Point’s Union Station is one of Indiana’s two carrier hotels, Lumen South Bend 1 offers 4,067 sq ft of DC-powered space at 1140 Franklin St, and Aunalytics runs a local data center.
Retail supply is thin. South Bend works for northern Indiana enterprises and regional disaster recovery, and it is too small for large deployments.
3. Fort Wayne
Fort Wayne has 15 listings and two of the state’s headline sites: Google’s campus and Lifeline Data Centers’ Fort Wayne facility, the largest retail colocation building in Indiana. Both are profiled below.
Indiana Michigan Power is headquartered in Fort Wayne, and its large-load tariff was written with northeast Indiana’s new campuses in mind.
The state approved expanding Google’s campus onto protected wetlands in 2025 despite local opposition. Fort Wayne suits regional enterprises and buyers who want an alternative to Indianapolis with a large retail building available.
4. Northwest Indiana: Hammond, Hobart, And La Porte
Northwest Indiana trades on its location next to Chicago and the rest of Illinois. Digital Crossroad Hammond, profiled below, sits on the state line, and NIPSCO serves most of the region on the MISO side of the grid.
AWS’s Hobart campus is the largest planned project in Indiana at 2,400 MW, part of a $15 billion Northern Indiana investment. Microsoft broke ground in La Porte in June 2026 after dropping its request for a local property tax abatement in March, and La Porte already holds 18 listings.
This region suits Chicago-area enterprises that want Indiana land costs and tax treatment, along with hyperscale and AI tenants building at gigawatt scale.
5. Central Indiana Ring: Lebanon, Frankfort, Pittsboro, And Morgan County
The newest hyperscale wave is landing in the counties around Indianapolis. Meta is developing a 1,000+ MW, 12-building campus in Lebanon’s LEAP district, and Logistix Property Group plans the 13-building, 300+ MW Logix I campus near Frankfort.
Vantage has three buildings planned on 285 of 618 rezoned acres in Pittsboro, and Google is building on 390 acres in Morgan County’s Monroe Township.
The pipeline is top-heavy. AWS Hobart and Meta Lebanon account for 3,400 MW of the 3,775 MW of planned capacity in Indiana that publishes a figure, about 90%. Two delays would empty most of it.
None of these sites offers retail space. They matter to hyperscalers, AI tenants, and the contractors who build for them.
Notable Colocation Providers And Facilities In Indiana
Indiana’s provider list starts with the five largest operating sites, two of them single-tenant hyperscale campuses, and continues with the retail operators where enterprise buyers can actually lease space.
The ten facilities below cover both groups.
1. AWS New Carlisle Data Center Campus (Project Rainier)
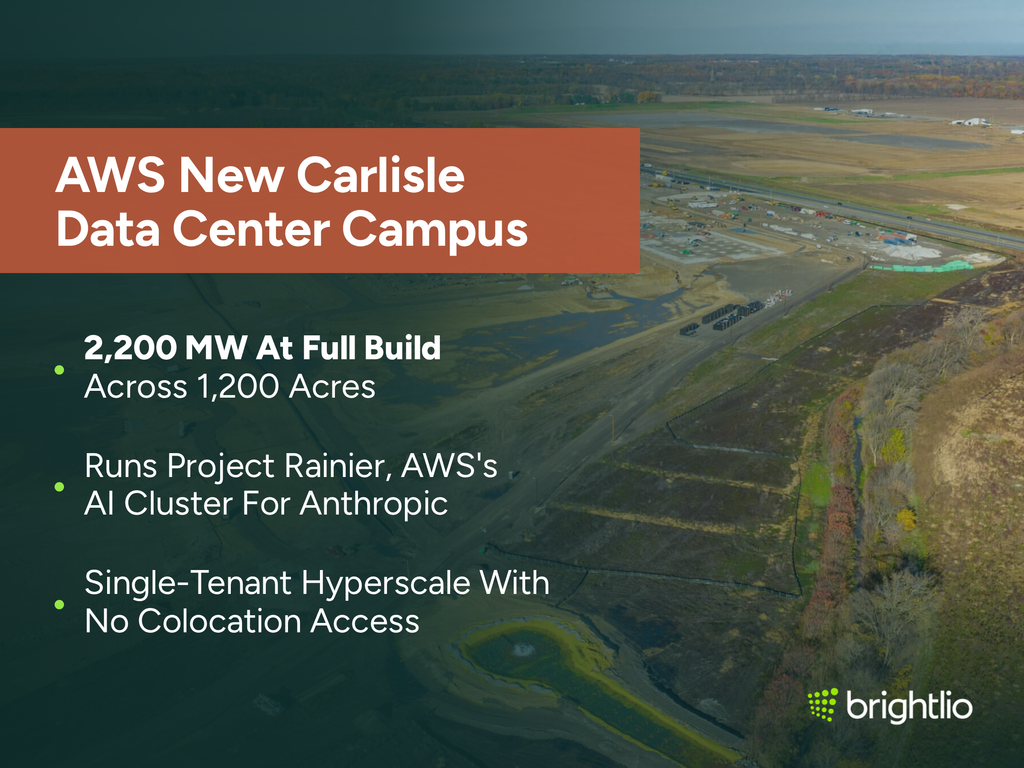
Amazon Web Services’ New Carlisle campus covers 1,200 acres in St. Joseph County and will draw 2,200 MW at full build. It came online in October 2025 and runs Project Rainier, the AI compute cluster AWS built for Anthropic.
The campus is the largest operating data center in Indiana. It sits in I&M territory on the PJM grid, under the large-load tariff AWS helped negotiate.
New Carlisle is a single-tenant hyperscale site with no colocation access. Its relevance to other buyers is the transmission and fiber investment it has pulled into northern Indiana.
2. Google Fort Wayne Data Center Campus
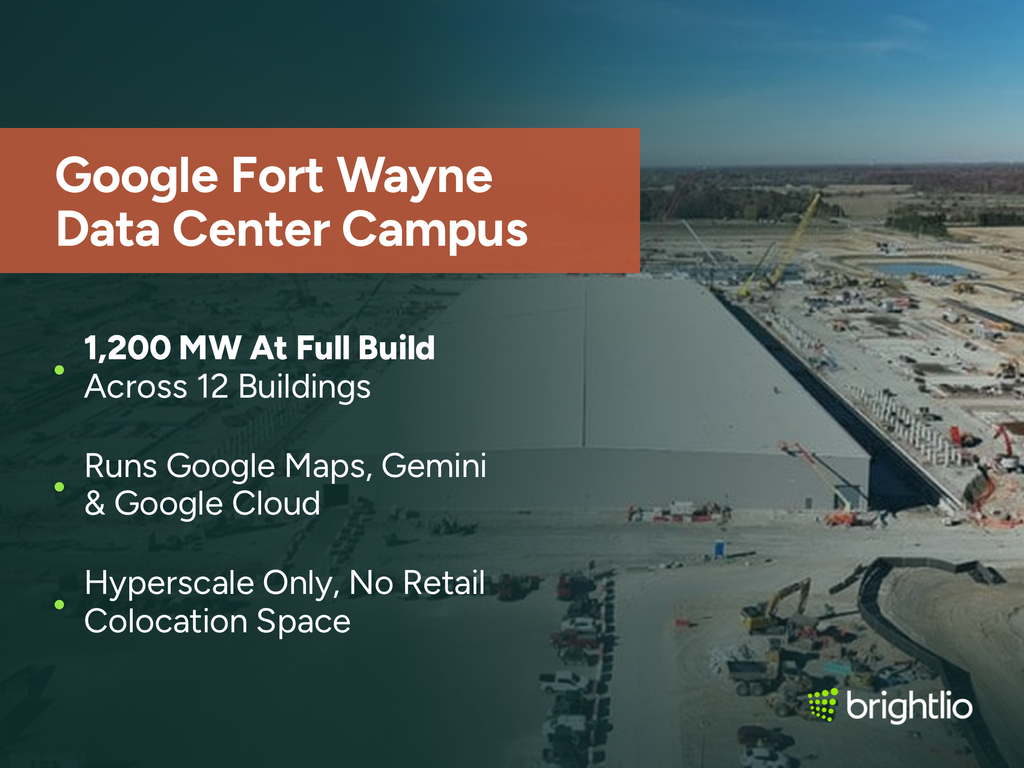
Google’s Fort Wayne campus is planned for 12 buildings on more than 700 acres, with 1,200 MW at full build and a $2 billion investment. The first phase has run since December 2025.
The site supports Google Maps, Gemini, and Google Cloud. In 2025, Google and I&M filed a custom demand-response contract with state regulators, which ties part of the campus load to grid conditions.
Like New Carlisle, Fort Wayne offers no retail space. It matters to other buyers as a sign that northeast Indiana can host gigawatt-scale load.
3. Digital Crossroad Hammond Data Center
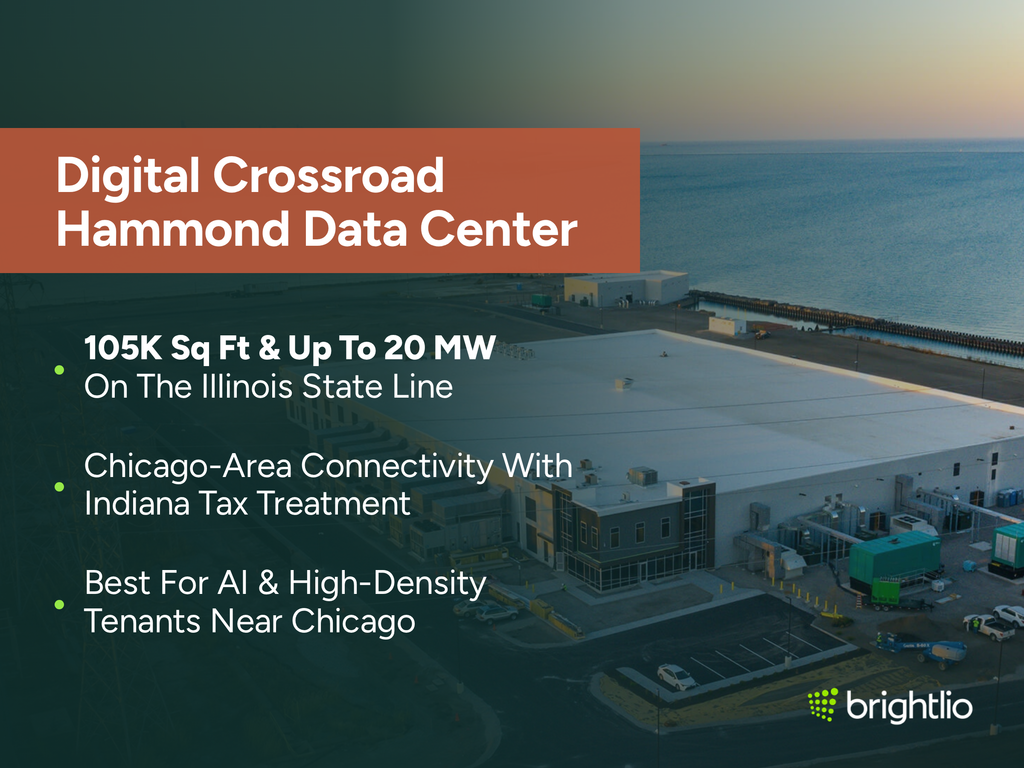
Digital Crossroad runs a 105,000 sq ft facility in Hammond that supports up to 20 MW, with CoreWeave as the tenant per city records.
The site sits on the Illinois state line, which gives tenants Chicago-area connectivity with Indiana tax treatment. With CoreWeave in place, buyers need to confirm available capacity before planning around it.
Digital Crossroad Hammond is best suited for AI and high-density tenants that want Chicago proximity without Chicago land costs.
4. DataBank IND2 Indianapolis Data Center
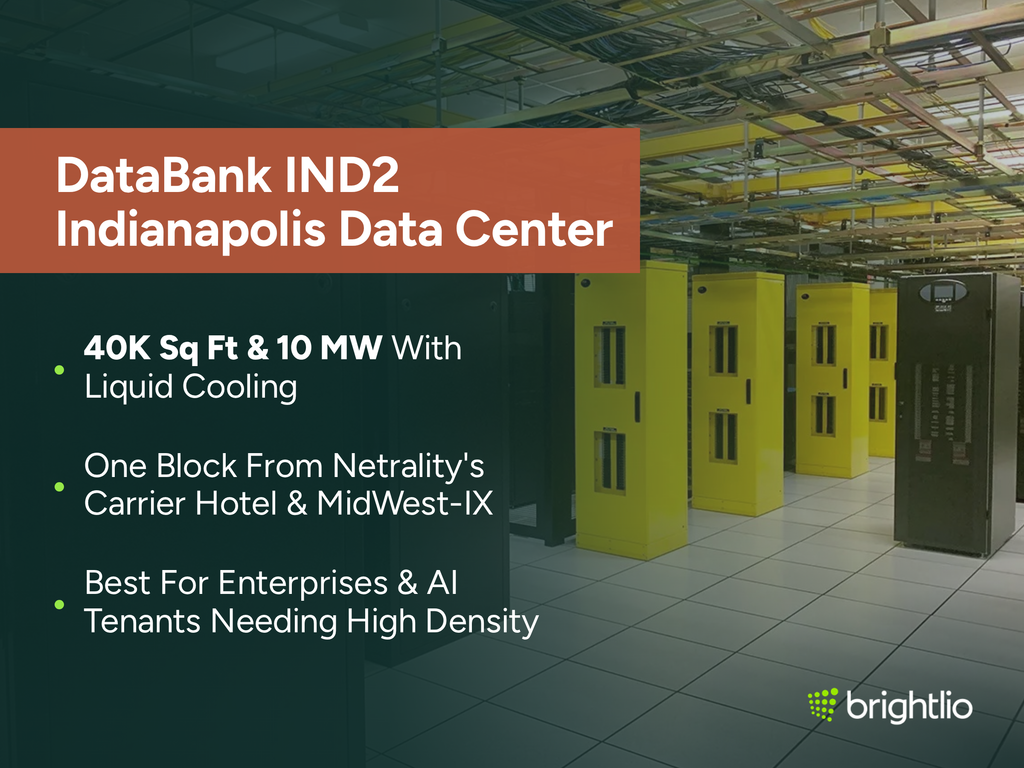
DataBank IND2 is a purpose-built 40,000 sq ft facility at 650 W Henry St with 10 MW of power and liquid cooling. DataBank acquired the site, formerly Lightbound, in 2018.
Its Henry Street address puts tenants a block from Netrality’s carrier hotel and the Midwest Internet Exchange. Liquid cooling sets it apart from the smaller downtown buildings, which run standard air-cooled cabinets.
DataBank IND2 is best suited for enterprises and AI tenants that need high-density racks with downtown interconnection.
5. Lifeline Data Centers Eastgate Campus
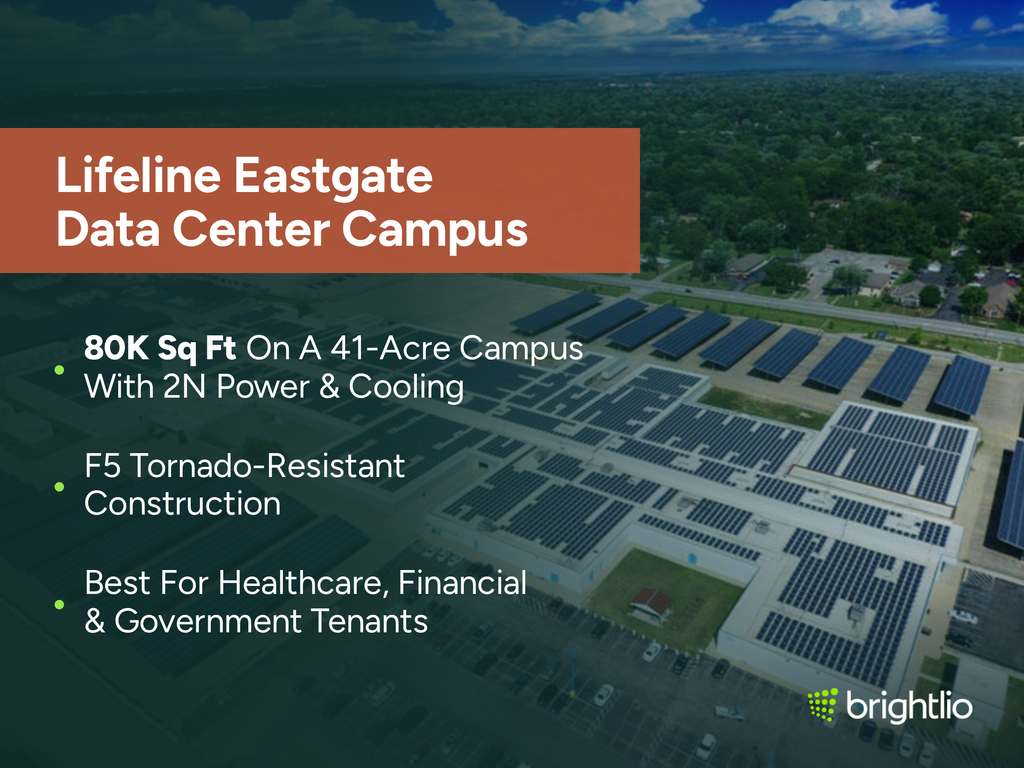
Lifeline Data Centers operates an 80,000 sq ft building with 2N power and cooling on a 41-acre campus at 401 N Shadeland Ave in Indianapolis. The company does not publish capacity.
Lifeline markets the building as F5 tornado resistant. That hardening speaks directly to Indiana’s leading natural hazard, and the 2N design removes single points of failure in power and cooling.
Lifeline Eastgate is best suited for healthcare, financial, and government tenants that need high redundancy and room to expand on one campus.
6. Netrality Indy Telcom Center
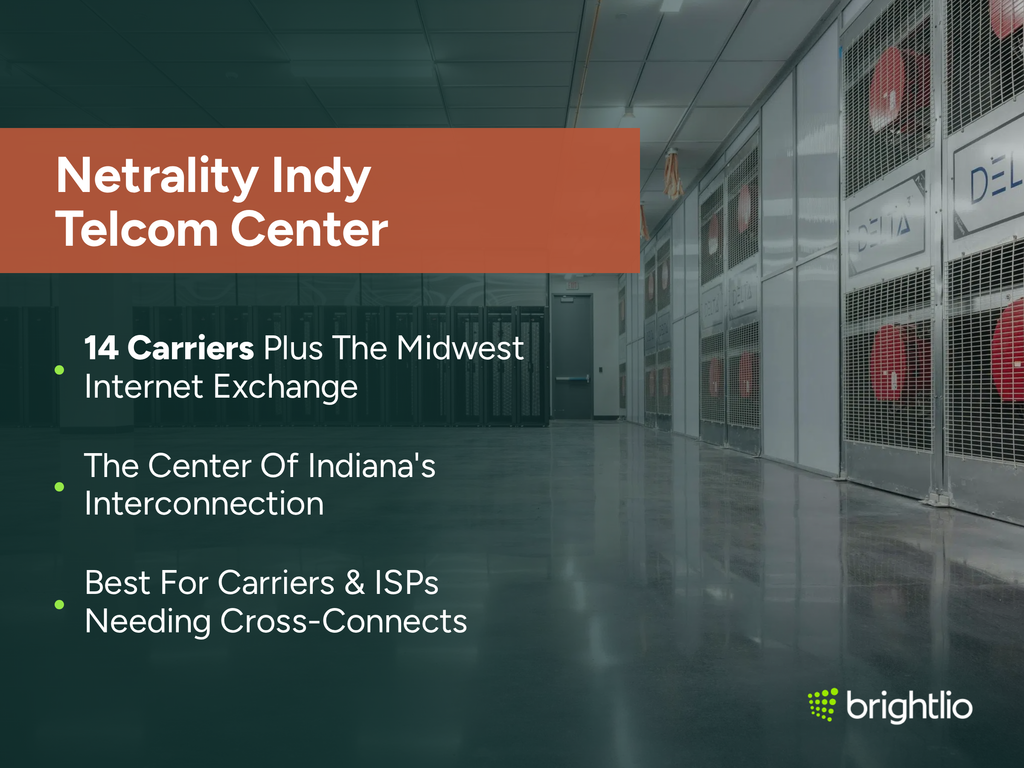
Netrality’s Indy Telcom Center spans 701 to 733 W Henry St and hosts 14 carriers along with the Midwest Internet Exchange. It is the center of Indiana’s interconnection.
Netrality runs carrier hotels in other central U.S. markets, including Kansas City, so multi-market network operators can standardize on one landlord.
Indy Telcom Center is best suited for carriers, ISPs, and enterprises that need direct cross-connects to multiple networks in Indianapolis.
7. Lifeline Data Centers Fort Wayne
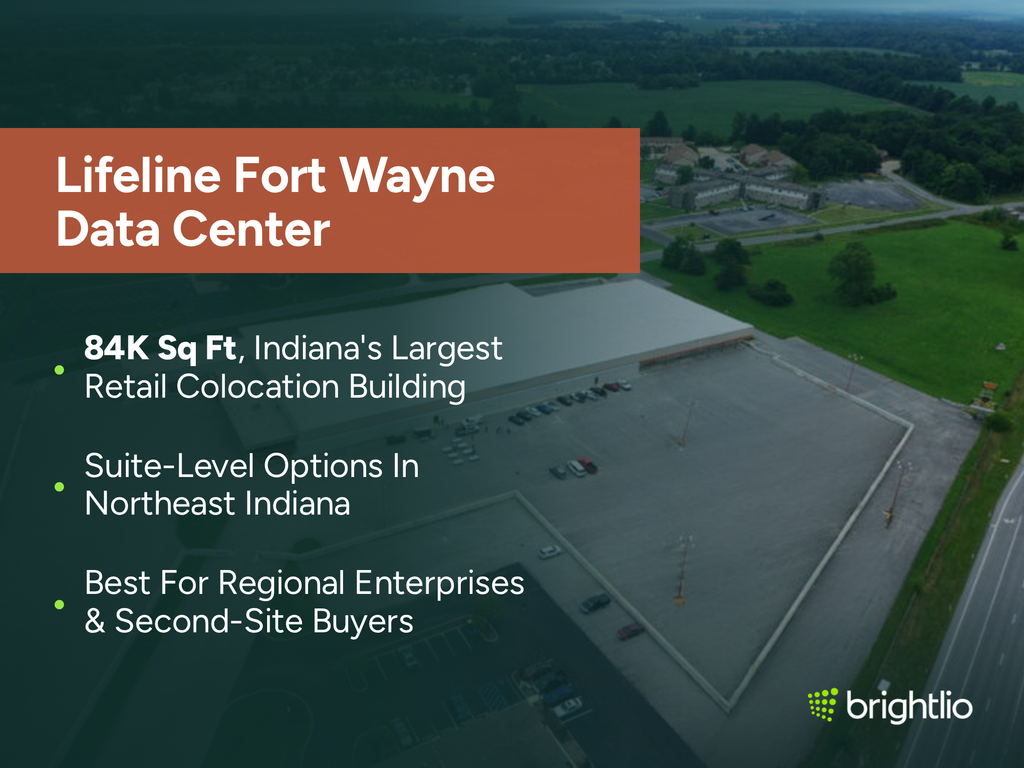
Lifeline’s Fort Wayne facility at 7601 S Anthony Blvd offers 84,000 sq ft of colocation and private cloud space, the largest retail colocation building in Indiana.
That size gives northeast Indiana buyers suite-level options that the downtown Indianapolis buildings cannot match.
Lifeline Fort Wayne is best suited for regional enterprises that need room to grow, and for Indianapolis firms that want a second site with the same operator.
8. Lumen Indianapolis 1
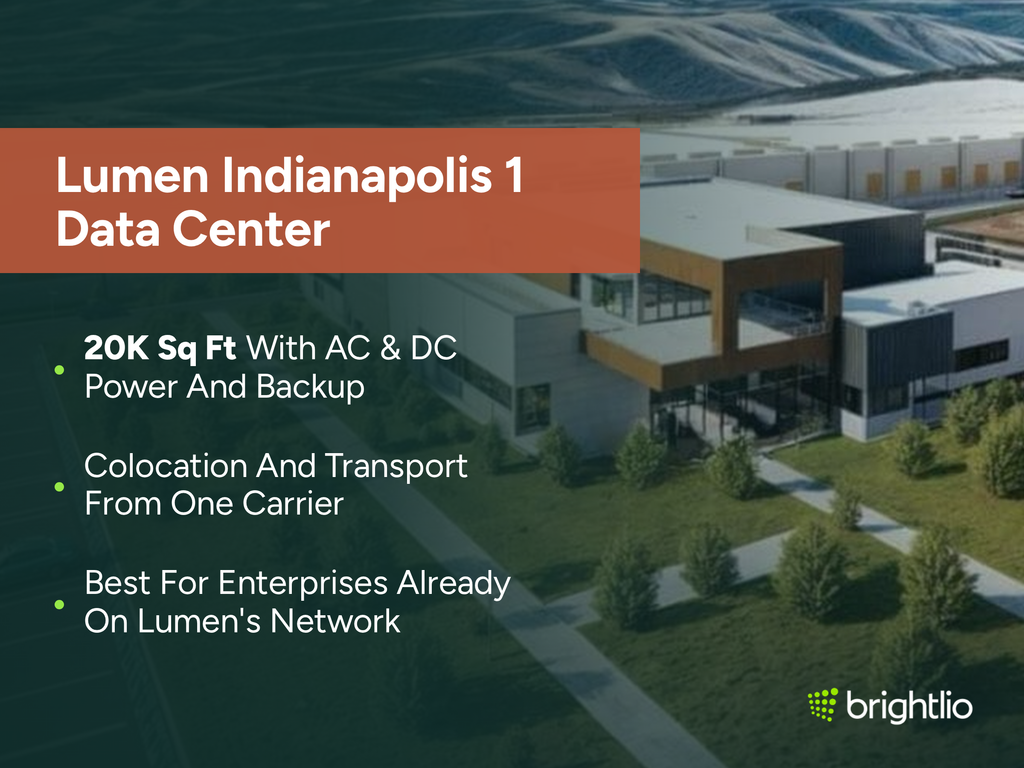
Lumen operates 20,000 sq ft at 1902 S East St, with AC and DC power and generator and battery backup.
Lumen pairs the space with its own national fiber network, so tenants can buy colocation and transport from one carrier.
Lumen Indianapolis 1 is best suited for enterprises already on Lumen’s network that want on-net colocation in Indianapolis.
9. US Signal Indianapolis IN02
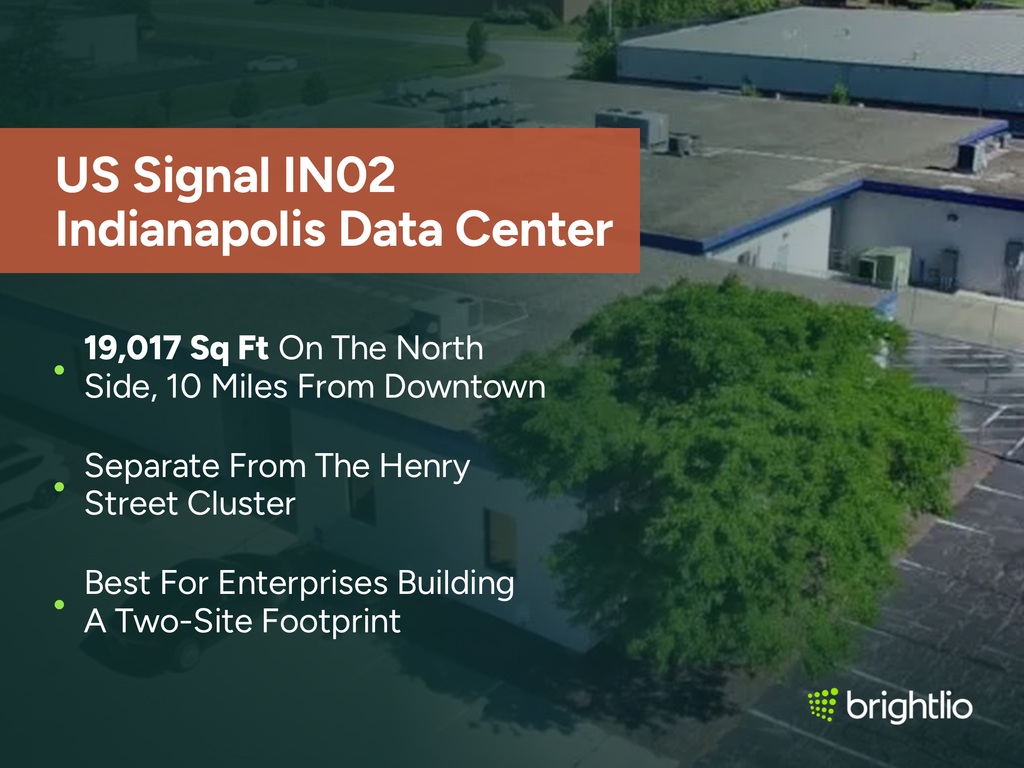
US Signal’s IN02 facility covers 19,017 sq ft at 6325 Morenci Trail on the north side, about 10 miles from downtown.
The location keeps it separate from the Henry Street cluster, which makes it a practical secondary site for buyers whose primary deployment sits downtown.
US Signal IN02 is best suited for enterprises building a two-site Indianapolis footprint for backup and recovery.
10. Global Access Point Union Station South Bend
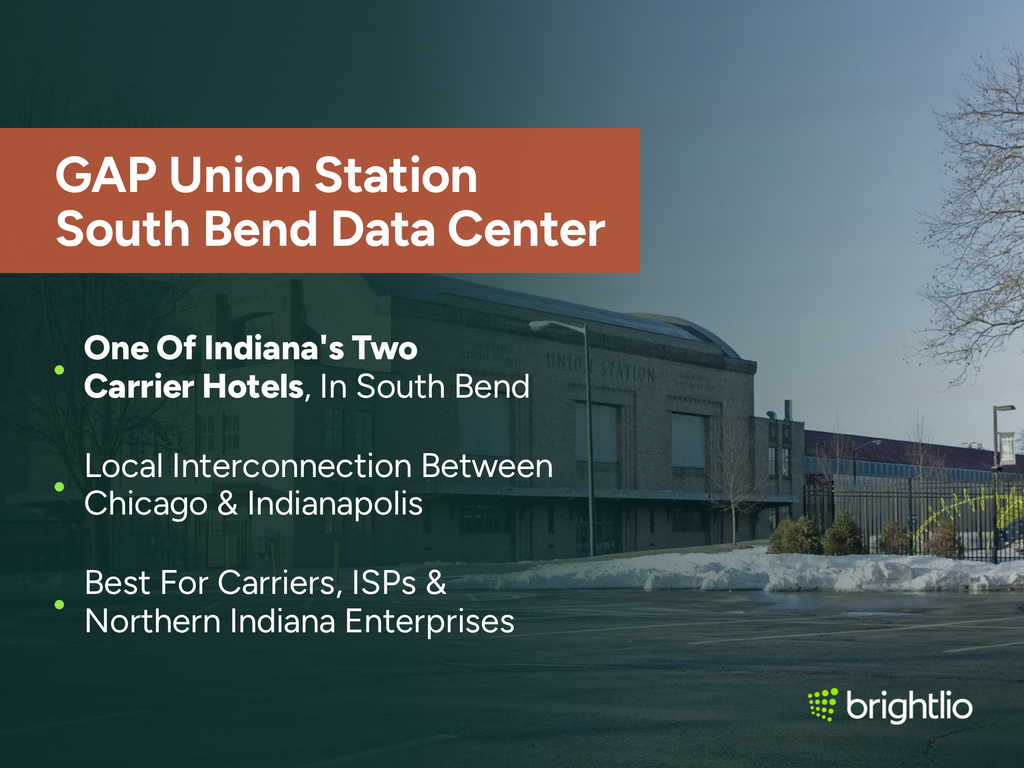
Global Access Point operates Union Station at 506 W South St in South Bend, which GAP describes as one of Indiana’s two carrier hotels. The company does not publish capacity.
Union Station gives northern Indiana a local interconnection point between Chicago and Indianapolis, close to the New Carlisle and La Porte campuses.
GAP Union Station is best suited for carriers, regional ISPs, and northern Indiana enterprises that need cross-connects without hauling traffic to Chicago.
Recent Developments In Indiana (Last 12 To 24 Months)
- June 2026: Microsoft broke ground on its La Porte campus, three months after dropping its request for a local property tax abatement. The project goes ahead on the state sales tax exemption alone.
- March 2026: Indiana passed House Bill 1210, keeping the 2019 data center sales tax exemption and adding a local payment of no more than 1% of exempt electricity sales tax for certificates issued after June 30, 2026. Critics called the payment toothless because existing certificate holders are excluded.
- February 2026: American Tower withdrew its Pike Township data center rezoning in Indianapolis after neighborhood opposition, the second large Marion County proposal to collapse in five months.
- December 2025: Google brought the first phase of its $2 billion Fort Wayne campus into service.
- October 2025: AWS brought its New Carlisle campus online, the first phase of a 1,200-acre site built for Project Rainier.
- September 2025: Google withdrew its 468-acre Project Flo rezoning in Franklin Township hours before the Indianapolis City-County Council was expected to vote it down.
- February 2025: The Indiana Utility Regulatory Commission approved I&M’s large-load settlement with AWS, Google, Microsoft, and consumer advocates, requiring 12-year minimum contracts and exit fees for new data center loads.
Drawbacks And Considerations For Colocation In Indiana
Indiana’s tax package is real, but it does not fix the market’s structural gaps. The five considerations below carry the most weight for buyers comparing Indiana with Chicago, Ohio, and other Midwest markets.
1. No Power Price Advantage
Indiana’s business rate sits slightly above the U.S. average. Buyers who choose a market on electricity cost will do better in states with cheaper power, and Indiana’s appeal rests almost entirely on tax treatment.
2. A Fossil-Heavy Grid
Coal and gas supply more than four-fifths of in-state generation. Companies with carbon commitments need renewable contracts or offsets, because the local grid will not get them there.
3. Thin Retail Colocation Supply
Indiana’s retail buildings are small, and the largest sits in Fort Wayne. Buyers needing multiple private suites, deep carrier choice, or dense cloud on-ramps will find more in Chicago.
4. Local Opposition And Approval Risk
Four major proposals have been withdrawn or abandoned since 2025 under local pressure. Anyone backing a new campus faces a real chance of losing the rezoning fight, and that risk is not priced into land or tax math.
5. A Market Built On Two Tenants
AWS and Google account for almost all of Indiana’s operating capacity, and two projects make up most of the planned pipeline. A shift in either company’s plans would reshape the market overnight.
How Brightlio Can Help With Colocation In Indiana
Brightlio helps organizations compare Indiana colocation, cloud connectivity, AI infrastructure, and disaster recovery options across Indianapolis, Fort Wayne, South Bend, Northwest Indiana, and nearby Midwest markets.
Our team helps clients evaluate facility fit, power pricing, carrier access, compliance needs, power density, cooling design, and long-term site risk.
We compare providers such as Netrality, DataBank, Lifeline Data Centers, Lumen, US Signal, Global Access Point, Digital Crossroad, and other Indiana operators.
For Indiana projects, we pay close attention to sales tax exemption certification, utility territory and large-load terms, PJM versus MISO exposure, tornado hardening, carrier routes to Chicago, local zoning risk, and expansion rights.
Brightlio can support cabinet, cage, private suite, single-tenant, high-density, AI, and multi-site disaster recovery planning, and our quotes come free to clients. Contact Brightlio to compare Indiana colocation solutions and start planning a cost-effective and resilient deployment.
[Request An Indiana Colocation Quote button]
Frequently Asked Questions
1. Which U.S. State Has The Most Data Centers?
Virginia has the most data centers in the United States, led by Northern Virginia’s Loudoun County cluster, and Texas and California follow among the top data center markets in the US. Indiana is a smaller market by listing count, with 125 data center listings, but its two largest campuses total 3,400 MW at full build.
2. How Many Data Centers Are In Indiana?
Indiana has 125 data center listings from 22 operators. Indianapolis holds 48, South Bend 28, La Porte 18, and Fort Wayne 15, with nine smaller markets sharing the remaining 16.
3. What Is The Largest Data Center In Indiana?
AWS’s New Carlisle campus is the largest, with 2,200 MW at full build for Project Rainier. Google’s Fort Wayne campus ranks second at 1,200 MW.
4. Who Is Building Data Centers In Indiana?
AWS, Google, Meta, and Microsoft lead Indiana’s buildout, joined by Vantage, Logistix Property Group, and Metrobloks. AWS’s 2,400 MW Hobart campus is the largest planned project in the state.
5. Are Indiana Electricity Costs Favorable For Colocation?
No. Indiana’s business rate averaged 13.93¢/kWh over the 12 months to July 2026, slightly above the 13.85¢/kWh U.S. average. Data centers choose Indiana for its tax treatment and land, and power costs about the same as the national norm.
6. What Tax Incentives Does Indiana Offer Data Centers?
Qualified data centers are exempt from Indiana’s 7% sales tax on equipment and electricity, with terms up to 50 years for investments above $750 million. Certificates issued after June 30, 2026 carry a local payment of no more than 1% of the exempt electricity sales tax.
7. Which Cities Are Best For Colocation In Indiana?
Indianapolis is the best fit for retail colocation, with the Henry Street carrier cluster and the widest choice of providers. Fort Wayne has the largest retail building in the state, South Bend offers a second carrier hotel, and Northwest Indiana suits buyers that want Chicago proximity.
8. Can Indiana Colocation Support AI Or High-Density Workloads?
Yes, though most AI capacity sits in single-tenant hyperscale campuses. For leasable space, DataBank IND2 offers liquid cooling in downtown Indianapolis, Digital Crossroad Hammond supports up to 20 MW with CoreWeave as tenant, and Metrobloks targets first capacity at its 75 MW Indianapolis site in Q1 2027.
9. Why Are People Protesting Against Data Centers In Indiana?
Residents object to the loss of farmland, water and electricity use, noise, and the scale of campuses near homes and schools. Google, QTS, Surge Development, and American Tower all withdrew Indiana proposals in 2025 and 2026 after local opposition.
10. Who May Not Need Indiana Colocation?
Buyers choosing a market for cheap power will find better rates elsewhere, and companies with carbon targets face a grid that runs mostly on coal and gas. Networks that depend on dense peering get more from Chicago.
Keep reading with our colocation guides for these nearby markets:
Tamzid is a cybersecurity researcher with 5+ years of experience across SaaS, security, compliance, data centers and cloud. He writes for brightdefense.com and hipaasimple.com, covering security, compliance, and infrastructure topics. Certified through Cisco, Fortinet (NSE 1), and the Basel Institute on Governance in OSINT, he grounds his work in primary sources and verified data.
Recent Posts
Data Centers In Indiana
Data Centers In Arizona
What Is a Data Center?
10 Largest AI Data Centers in the World
Let's start
a new project together